Key Takeaways
-
An orthodontic lifetime maximum is a one-time total cap on what your plan pays for one person's braces or aligners, and it usually does not renew each year.
-
The lifetime maximum caps the insurer's payment, not your total cost: a 50% plan with a $1,500 cap on a $6,000 treatment leaves you paying at least $4,500.
-
The orthodontic maximum is usually separate from your annual dental maximum, but confirm this with your insurer, since some plans combine the two.
-
Plan rules on age limits, waiting periods, in-network requirements, and retainer coverage can change what you actually receive, so check them before starting.
-
Ask your insurer for your remaining orthodontic benefit and request a written predetermination of benefits to share with your orthodontist before treatment begins.
-
Ask whether earlier orthodontic payments count toward your lifetime maximum, especially if you are seeking retreatment or switching plans mid-treatment.
You finally found the right orthodontist, and your plan says it covers braces. Then you spot two little words in the benefits booklet: lifetime maximum. Suddenly the coverage feels a bit more confusing. Don’t worry, you are not alone. Almost every family we meet at Brockway Orthodontics asks about it.
Here is the good news. Once you understand how the orthodontic lifetime maximum works, it is easy to plan around. In this guide, we will keep things simple and friendly. You will learn what the term means, how it is different from your yearly dental limit, and what to ask before treatment starts. We will also share a few real-world examples with easy math.
One quick note: every dental plan is different. The details below are general. Your own plan document always has the final say, so use this guide to ask smart questions and stay in control of your costs in 2026.
The Quick Answer: What Is an Orthodontic Lifetime Maximum?
An orthodontic lifetime maximum is the total dollar amount your dental plan will pay toward covered orthodontic care for one eligible person. It usually does not renew each year. Once the plan has paid that amount, it stops paying for orthodontic treatment, even if your bill is not finished.
Think of it like a gift card that you can only use once. If the card holds $1,500, that is all the plan will ever put toward braces or aligners for that person. It does not matter how many years your treatment takes.
Here are the key points in plain language:
- It is a total cap on what the insurer pays. It is not a cap on what the orthodontist charges.
- It is usually a one-time limit, not a yearly one.
- It is often per person, not per family. A child with $1,500 in benefits does not share that with a sibling.
- The exact rules depend on your policy. Some plans count earlier orthodontic payments. Others do not.
The word “lifetime” sounds permanent, but it is really about your plan’s terms. It should not be treated as a promise that follows you from job to job or insurer to insurer.
Thing 1: Your Orthodontic Maximum Is Usually Separate From Your Annual Maximum
Many people mix up these two limits. They are different, and knowing the difference can save you from a surprise.
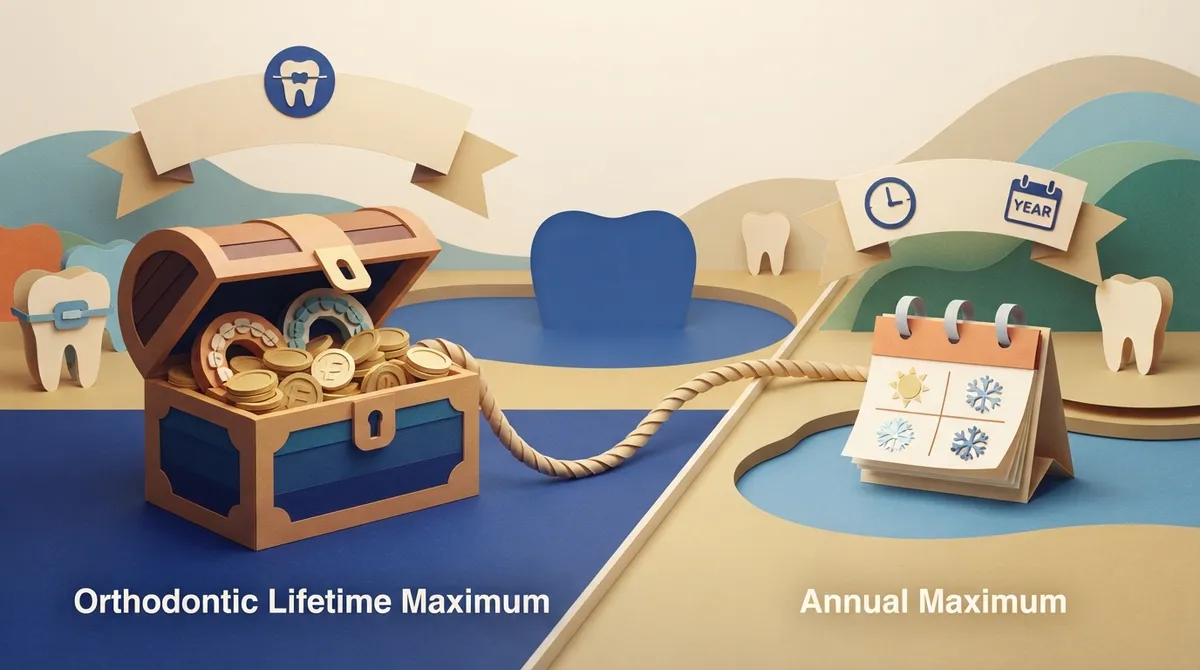
Annual maximum versus orthodontic lifetime maximum
Your annual maximum is the most your plan pays in a plan year for everyday dental care. That means things like exams, cleanings, fillings, and crowns. It resets each year.
Your orthodontic lifetime maximum is a separate bucket just for braces, aligners, and related care. In many plans, using one does not drain the other. Still, benefit designs vary, so check your plan documents to be sure.
| Feature | Annual Dental Maximum | Orthodontic Lifetime Maximum |
|---|---|---|
| What it covers | Exams, cleanings, fillings, crowns | Braces, aligners, retainers (if covered) |
| How often it resets | Every plan year | Usually never |
| Who it applies to | Each covered member | Each eligible member |
| Typical use | Ongoing care | One course of treatment |
Why does this matter? Let’s say your child needs two fillings this year and also starts braces. If the two limits are separate, the fillings should not eat into the braces benefit. But if your plan combines them, you could hit your cap sooner than expected. A quick call to your insurer clears this up.
If you want a deeper look at how coverage fits into your budget, our guide on how to use dental insurance to help pay for braces walks through the basics step by step.
Thing 2: The Cap Limits the Insurer’s Payment, Not Your Total Cost
This is the part that surprises families most. Your plan may say it pays 50% of orthodontic care. That sounds great. But the lifetime maximum puts a ceiling on what that 50% can add up to.
A simple example with real math
Let’s walk through a common setup, using the numbers many insurers publish as examples.
- Your eligible orthodontic treatment costs $6,000.
- Your plan pays 50% of eligible charges. That would be $3,000.
- But your orthodontic lifetime maximum is $1,500.
- The plan stops at $1,500, not $3,000.
- You pay the rest: at least $4,500, before any deductibles or non-covered charges.
See how the cap changes the picture? The percentage looked generous. The lifetime maximum is what really decides your insurance payment.
For context, one major insurer’s overview lists typical metal braces costs of about $3,000 to $7,000. It also notes that some plans may cover up to 50% of children’s braces with a $1,500 lifetime maximum per child. Another insurer example describes 50% coinsurance up to a $1,500 lifetime maximum. These are examples of plan designs, not industry-wide rules. Some plans offer $1,000, $2,000, or higher. There is no single standard.
What this means for your budget
Instead of asking, “What does my plan cover?” try asking, “How much will my plan pay in total, and what is my share?” That small shift in thinking makes planning much easier. Many families pair their insurance benefit with a monthly payment plan so the remaining balance feels manageable. You can explore options in our guide to braces monthly payment plans.
It also helps to know that treatment length and complexity can shape the final fee. Our articles on how treatment length affects orthodontic costs and how treatment complexity affects fees explain why prices can differ from one smile to the next.
Thing 3: Plan Rules Can Change What You Actually Receive
The lifetime maximum is only one piece. Several other rules decide whether you can use that benefit and when. Here are the big ones to watch for.
Age limits and who is eligible
Coverage is not universal. Some plans cover children only. Some cover adults and children. Some cover neither. Do not assume that a plan covering your teen also covers your own braces. If you are an adult thinking about treatment, this is the first thing to check.
We cover this topic in more detail in which orthodontic insurance age limits should you check, and in our guide on getting answers to adult orthodontic insurance questions.
Waiting periods and treatment already started
Many plans have a waiting period before orthodontic benefits begin. Some plans also exclude treatment that began before your coverage started. If you are switching offices, insurers, or jobs mid-treatment, ask exactly how the plan handles care in progress. Our post on orthodontic coverage for treatment already started covers the common questions.
In-network rules and payment timing
Some plans require you to see an in-network provider. Others pay the benefit in pieces over the course of treatment instead of all at once when the appliance goes on. That means your insurance check may arrive slowly, while your practice payment plan runs on its own schedule. Knowing this up front avoids confusion later.
Retainers and replacements
Plans may have special rules for retainers or replacement appliances. Some include them in the lifetime maximum. Others exclude them. Since retainers matter for keeping your results, it is smart to ask. Our guide on how to budget for retainer price after braces can help you plan.
How to Find Out How Much of Your Maximum Remains
If you have used orthodontic benefits before, or you are not sure what you have left, here is a simple way to find out.
- Find your plan documents. Look for the orthodontic section in your benefits booklet or online member portal.
- Call the number on your insurance card. Ask for your orthodontic lifetime maximum and the remaining amount for each person.
- Ask how past payments count. Earlier orthodontic payments, even from a different plan, may or may not reduce your benefit.
- Request a written estimate. Ask the insurer for a predetermination of benefits for your planned treatment.
- Share it with your orthodontist. Our team can then match your treatment plan and payment options to your real benefit.
Getting numbers in writing is a great habit. Verbal answers can be forgotten or misunderstood. A written predetermination gives you something solid to plan around.
Smart Questions to Ask Before You Start Treatment
Bring this short list to your insurer or to your consultation. It covers the details that matter most.
- What is the orthodontic lifetime maximum, and is it per person?
- What percentage of eligible charges does the plan pay?
- Does the maximum apply to adults, or only to children?
- Is there a waiting period before benefits start?
- Do I need to use an in-network orthodontist?
- How are benefits paid: at the start, or over the length of treatment?
- Are retainers or replacement appliances included?
- How are previous orthodontic payments counted?
- What happens if my coverage changes during treatment?
Asking these questions does not make you difficult. It makes you prepared. Our team is happy to help you sort through the answers. If you want a head start, our post on orthodontic insurance mistakes Clearwater families make shares the most common slip-ups.
Which Types of Treatment Can Use Your Benefit?
Your orthodontic lifetime maximum may apply to different treatment types, depending on the plan. Many plans treat braces and clear aligners similarly, but some have their own limits. Brockway Orthodontics offers metal braces, ceramic (clear) braces, and Spark™ Clear Aligners, which is a more affordable alternative to Invisalign. Having several options means you can pick what fits your smile, your lifestyle, and your budget.
If you are weighing choices, these guides may help:
- Clear aligners vs. braces cost: which is worth it?
- Metal vs. ceramic braces: which is right for you?
- What are Spark clear aligners? A guide for families
Tips for Different Kinds of Patients
Parents of kids and teens
Children’s coverage is the most common type. Check whether your plan sets a cutoff age, because some plans stop at 18 or 19. If your child may start treatment close to that age, timing could matter. Our guide on how to budget for teen orthodontic treatment can help you plan ahead.
Teens and young adults
If you are 18 to 25, you may be moving off a parent’s plan and onto your own. Ask how that change affects your remaining orthodontic benefit. Keep a copy of any written estimate, since it can help if your coverage changes.
Adult professionals
Many adult plans exclude orthodontics altogether. That does not mean treatment is out of reach. Flexible payment plans and discreet options like ceramic braces and clear aligners can fit a busy schedule. See our guide on how to find an orthodontist that takes my insurance for helpful next steps.
Retreatment and relapse patients
If you had braces years ago and need a touch-up, ask whether your earlier orthodontic payments used up your lifetime maximum. Some plans count prior payments, and some do not. It is one of the most important questions for retreatment patients.
The Bottom Line on Your Orthodontic Lifetime Maximum
Here is the quick recap. An orthodontic lifetime maximum is a total cap on what your plan pays toward orthodontics for one eligible person. It is usually separate from your yearly dental limit. It controls the insurer’s payment, not the orthodontist’s fee. And plan rules about age, waiting periods, and network can change how much you really get.
The best move is to verify your remaining benefit, ask for a written estimate, and talk with your orthodontist before treatment starts. That way, there are no surprises, only a clear plan and a smile you will love.
Ready to see how your benefits fit your treatment? Our friendly team is here to walk you through it. Book your appointment online or contact us with your insurance questions. You can also visit our Brockway Orthodontics location on Google to read what Clearwater families say about us. For general dental health information, the American Dental Association is a trusted resource, and you can learn more about orthodontic care in our state from the Florida Association of Orthodontists. Dr. Brockway and our team are proud to be Clearwater’s go-to orthodontist for families, and we would love to help you plan every step.
FAQs
Q: What does an orthodontic lifetime maximum mean?
A: It is the total amount your dental plan will pay toward covered orthodontic care for one eligible person. Once you reach that limit, the plan stops paying for orthodontics. The exact rules depend on your policy, so it is always smart to check your plan documents.
Q: Does the orthodontic lifetime maximum reset every year?
A: Usually not. Unlike your annual dental maximum, the orthodontic lifetime maximum is typically a one-time cap that does not renew each plan year. Some plans may count earlier payments, so ask your insurer how yours works.
Q: Is the orthodontic maximum separate from my annual dental maximum?
A: In many plans, yes. Everyday care like cleanings and fillings usually falls under the annual maximum, while braces and aligners fall under the orthodontic limit. Benefit designs vary, so confirm with your insurer before treatment starts.
Q: Does orthodontic insurance cover adults as well as children?
A: Not always. Some plans cover only children, some cover adults and children, and some cover neither. Age limits and dependent rules vary, so never assume that a plan covering a child’s braces also covers adult treatment.
Q: How can I find out how much of my orthodontic lifetime maximum is left?
A: Call the number on your insurance card or check your member portal, then ask for the remaining orthodontic benefit for each person. It also helps to request a written predetermination of benefits. Our team at Brockway Orthodontics can help you match your treatment plan to what your insurer tells you.
Our Service Area